Buying a home is an exciting step, but it can also feel overwhelming if you don’t know where to begin. From choosing the right neighborhood to comparing mortgage options and estimating your monthly expenses, there are many things to consider before making an offer.
For first-time buyers especially, finding a house is about more than choosing a property that looks good online. You also need to think about your budget, property taxes, maintenance costs, closing expenses, and homeowners insurance.
If you are searching for how to find a house in the US, this guide will walk you through the main steps of the home buying process and explain why home insurance should be part of your planning from the beginning.
Buying a home in the U.S. involves more than finding the right property.
Step 1: Determine Your Home Buying Budget
Before you start visiting properties or browsing online listings, take some time to understand what you can realistically afford.
Many buyers focus on the home’s purchase price and monthly mortgage payment. However, the real cost of owning a home includes several other expenses.
Your monthly housing budget may include:
-
Mortgage principal and interest
-
Property taxes
-
Home insurance
-
HOA fees
-
Utilities
-
Maintenance and repairs
-
Mortgage insurance, if applicable
Thinking about these costs early can help you avoid choosing a home that looks affordable at first but becomes difficult to manage after closing.
Think Beyond the Purchase Price
For example, two homes with the same purchase price can have very different ownership costs.
One property may have:
-
Lower property taxes
-
No HOA
-
A newer roof
-
Lower home insurance costs
Another property could have higher taxes, HOA fees, an older roof, or higher insurance premiums.
That’s why your home buying budget should include more than just the listing price.
Step 2: Plan for Your Down Payment and Closing Costs
Your down payment is one of the biggest expenses when buying a house, but it isn’t the only upfront cost.
Depending on your mortgage and location, you may also need money for:
-
Loan-related fees
-
Home appraisal
-
Inspection
-
Title-related expenses
-
Property taxes
-
Prepaid insurance
-
Escrow
-
Closing costs
-
Moving expenses
Understanding these costs before you start your home search can help you determine how much cash you actually need.
If you’re a first-time homebuyer, don’t hesitate to ask your lender to explain each major expense. Knowing what you’re paying for can make the closing process much easier to understand.
Step 3: Get a Home Insurance Quote Before Buying
One of the most overlooked parts of the home buying process is insurance.
Many buyers wait until the last minute to think about homeowners insurance. In reality, you should start looking into insurance costs while you’re still comparing properties.
If you’re financing your home with a mortgage, your lender will generally want proof that the property is insured before the loan can close.
More importantly, getting an early home insurance quote gives you a better idea of what owning the property will actually cost.
What Can Affect Home Insurance Costs?
The price of a home insurance policy can vary depending on several factors, including:
-
Location
-
Age of the home
-
Roof condition
-
Construction materials
-
Property size
-
Coverage limits
-
Deductible
-
Previous claims
-
Local weather risks
-
Additional coverage needs
For example, a newer home with an updated roof may have different insurance costs from an older property that needs repairs.
That’s why it makes sense to compare home insurance quotes before you finalize your purchase.
If you’re currently looking for coverage, you can learn more about your options on our Home Insurance page.
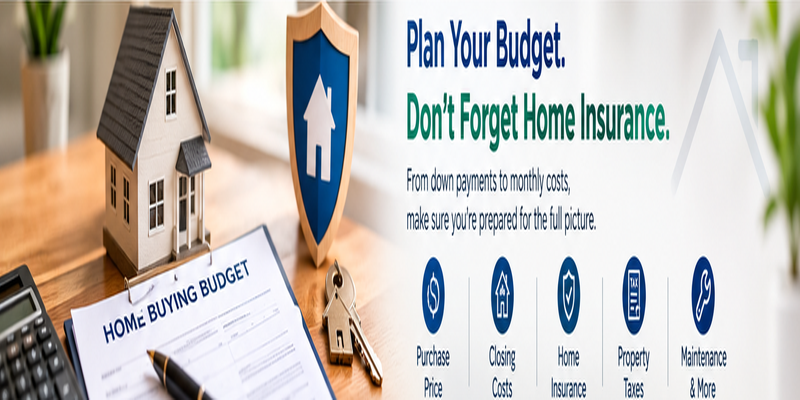
Your home buying budget should include more than the purchase price.
Step 4: Choose the Right Location
When learning how to find a house, location should be one of your biggest considerations.
A beautiful house may not be the right choice if the location doesn’t fit your lifestyle or budget.
Think about:
-
Distance to work
-
Schools
-
Public transportation
-
Grocery stores
-
Restaurants
-
Healthcare
-
Local property taxes
-
HOA fees
-
Neighborhood conditions
-
Weather and natural disaster risks
You should also consider how the location could affect your home insurance cost.
Some areas may have greater exposure to hurricanes, flooding, wildfires, or severe storms. These risks can affect insurance availability, coverage options, and premiums.
So when comparing homes, don’t just ask:
“How much does this house cost?”
Also ask:
“How much will it cost to own this house?”
Step 5: Decide What Type of Home You Want
There isn’t one type of property that is right for every buyer.
Your choices may include a single-family home, condominium, townhouse, or other property type.
Single-Family Homes
A single-family home can provide more privacy and greater control over the property.
However, you are generally responsible for maintenance and repairs, including things such as:
-
Roof maintenance
-
Plumbing
-
HVAC systems
-
Landscaping
-
Fencing
-
Exterior repairs
When estimating your budget, leave some room for unexpected maintenance expenses.
Condos and Townhomes
Condos and townhomes may have shared areas and HOA management.
The HOA may handle certain exterior maintenance responsibilities, but you will typically have HOA fees and rules to consider.
Before buying, review:
-
Monthly HOA fees
-
HOA rules
-
Special assessments
-
What the HOA’s insurance covers
-
What you need to insure yourself
Don’t assume that the HOA’s insurance policy automatically covers everything inside your unit.
Your own homeowners insurance or condo insurance may still be needed for personal belongings, liability, and other covered risks.
Step 6: Start Your Home Search
Once you know your budget and preferred location, you can begin actively searching for properties.
Online real estate platforms can make it easier to compare homes based on:
-
Price
-
Location
-
Bedrooms
-
Bathrooms
-
Square footage
-
Lot size
-
Year built
-
HOA fees
-
Property taxes
Working with a local real estate professional can also help you understand the market and the buying process.
Don’t Rely Only on Listing Photos
Online photos can make a property look perfect, but they don’t always tell you everything.
When visiting a property, pay attention to:
-
Roof condition
-
Water damage
-
Cracks
-
Windows
-
Electrical systems
-
Plumbing
-
HVAC
-
Signs of moisture or mold
-
General maintenance
A house that needs significant repairs may cost much more than the initial purchase price suggests.
Step 7: Schedule a Home Inspection
A professional home inspection is an important part of buying a house.
An inspection can help identify potential problems before you complete the purchase.
Depending on the property, an inspector may evaluate areas such as:
-
Foundation
-
Roof
-
Plumbing
-
Electrical systems
-
Heating and cooling
-
Windows and doors
-
Attic
-
Insulation
-
Insulation
-
Structural components
A home inspection doesn’t guarantee that every issue will be discovered, but it can give you a much clearer picture of the property’s condition.
If major problems are found, you may be able to discuss repairs or other terms with the seller before closing.
Step 8: Compare Mortgage Options
If you’re financing the property, you’ll need to compare mortgage options and understand your total monthly payment.
Don’t look only at the interest rate.
Consider:
-
Monthly principal and interest
-
Down payment
-
Mortgage insurance
-
Property taxes
-
Home insurance
-
HOA fees
-
Closing costs
-
Escrow
Your actual monthly housing expense may be significantly different from the mortgage payment shown in an online calculator.
This is another reason why getting a home insurance quote early can be useful.
Step 9: Understand Your Home Insurance Coverage
Choosing a home insurance policy isn’t simply about finding the lowest price.
You should understand what you’re actually paying for.
Depending on the policy, homeowners insurance coverage may include protection for areas such as:
Dwelling Coverage
This generally relates to the physical structure of your home and covered damage, subject to the policy’s terms, limits, and exclusions.
Personal Property Coverage
This can help protect covered belongings such as furniture, clothing, electronics, and other personal items.
Personal Liability Coverage
Liability coverage can help protect you financially if you are legally responsible for certain injuries or property damage involving another person.
Additional Living Expenses
Some policies may provide coverage for certain additional living expenses if a covered loss makes your home temporarily unlivable.
The exact coverage depends on the insurance policy you purchase, including its limits, deductible, exclusions, and covered causes of loss.
Step 10: Check Whether You Need Additional Insurance
A standard home insurance policy does not necessarily cover every type of property damage.
For example, homeowners may need to consider additional coverage depending on where the property is located and the risks associated with it.
Flood Insurance
Flood damage is generally not covered by a standard homeowners policy.
If you’re buying a property in an area with flood risk, ask about flood insurance before completing the purchase.
Other Additional Coverage
Depending on the property and location, you may also need to discuss additional coverage options with an insurance professional.
The important thing is to understand your risks before you buy-not after a major loss occurs.
Step 11: Review Everything Before Closing
Once your offer is accepted, the process isn’t finished yet.
Before closing, review your:
-
Mortgage documents
-
Closing costs
-
Property taxes
-
Insurance premium
-
Deductible
-
Escrow amount
-
Loan terms
-
Insurance coverage
Make sure the information matches what you expected.
You should also confirm that your home insurance policy is active and that your lender has the required proof of insurance before closing.
How Much Does Home Insurance Cost?
There is no single price for homeowners insurance.
Your premium can vary depending on:
-
Where the home is located
-
The age of the property
-
The home’s construction
-
Roof condition
-
Coverage limits
-
Deductible
-
Claims history
-
Local risks
This is why two homeowners with similar houses can receive very different home insurance quotes.
Rather than estimating based on another person’s policy, it’s better to request a quote based on the actual property you are considering.
Frequently Asked Questions About Finding a House
What is the first step when looking for a house?
The first step is usually understanding your budget. Consider your down payment, mortgage payment, property taxes, home insurance, HOA fees, maintenance, and other ongoing expenses before beginning your home search.
When should I get homeowners insurance?
It’s a good idea to research home insurance quotes while you’re shopping for a property rather than waiting until the closing date. This allows you to include insurance in your overall homeownership budget.
Do I need homeowners insurance to buy a house?
If you’re using a mortgage, your lender will generally require homeowners insurance as part of the loan requirements. The exact requirements can vary by lender and loan.
Is home insurance included in my mortgage payment?
In many cases, homeowners insurance and property taxes may be collected through an escrow account as part of your monthly mortgage payment. Your lender can explain how your specific loan handles these expenses.
Does homeowners insurance cover flood damage?
Standard homeowners insurance generally does not cover flood damage. If your property has flood exposure, you should ask about separate flood insurance.
Should I choose the cheapest home insurance quote?
Price is important, but it shouldn’t be the only factor. Compare the coverage limits, deductible, exclusions, and protections included in each policy so you understand what you’re actually purchasing.
The right home also needs the right protection. Comparing homeowners insurance coverage and understanding your risks can help you protect your property, belongings, and financial future.